RED BULL FROM ½ PALLET · FREE UK SHIPPING FROM 1 PALLETWhatsApp +44 7999 150302 ↗
How to Calculate Your Wholesale Drinks Profit Margin in the UK
Learn how UK retailers calculate wholesale drinks profit margin using VAT-aware shelf prices, landed cost, delivery charges and a practical 24-can case example.

A case of drinks can look like a bargain on a wholesale price list, but the number that matters to a shopkeeper is what remains after the stock has been delivered and sold. That is your wholesale drinks profit margin—and it is surprisingly easy to overestimate if you compare a supplier’s ex-VAT case price with the VAT-inclusive price on your shelf. Whether you run a corner shop, convenience store or forecourt, a few straightforward calculations will tell you how much room you really have for delivery costs, promotions and slow-moving flavours.
There is no single “correct” margin for every drink or every retailer. A fast-selling chilled can in a busy location is a different proposition from a slower-moving flavour held in the stockroom. The aim here is not to promise a particular return. It is to show you how to work out the figures for your own business, using a realistic worked example with deliberately illustrative prices, not a TRIMAYU quotation or recommended retail price.
Wholesale drinks profit margin: know the difference between margin and markup
Gross profit per can is your selling price before VAT minus the cost of that can before VAT, where input VAT is recoverable. Gross margin measures that profit as a percentage of the selling price; markup measures it as a percentage of the cost. They sound similar, but they are not interchangeable. HMRC explains this distinction in its guidance on gross profit and markup rates.
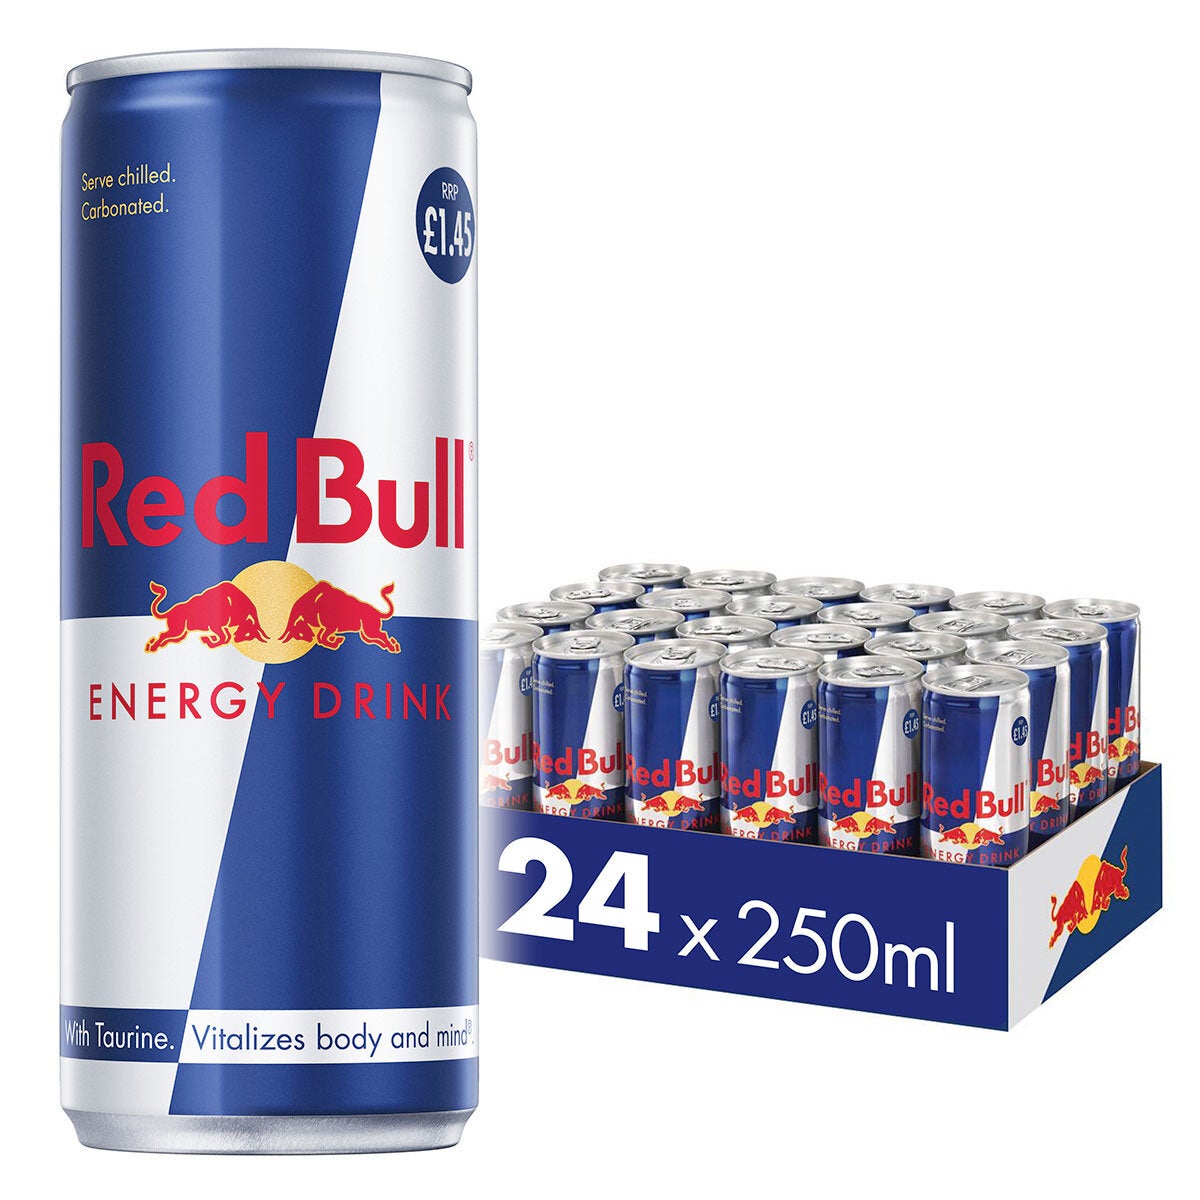
For example, imagine buying a 24-can wholesale case for £18.00 excluding VAT and selling each can for £1.50 including 20% VAT. A VAT-registered retailer making a standard-rated sale has net sales revenue of £1.25 per can (£1.50 ÷ 1.20). The case costs £0.75 per can (£18 ÷ 24). Before delivery and other costs, that leaves £0.50 gross profit per can: a 40% gross margin (£0.50 ÷ £1.25), but a 66.7% markup (£0.50 ÷ £0.75). Both percentages describe the same 50p gross profit; they simply use different denominators.
| Illustrative 24-can case calculation | Value |
|---|---|
| Wholesale case cost, ex VAT | £18.00 |
| Number of cans | 24 |
| Cost per can, ex VAT | £0.75 |
| Example shelf price, inc VAT | £1.50 |
| Net selling price, ex VAT | £1.25 |
| Gross profit per can before freight | £0.50 |
| Gross margin before freight | 40% |
| Markup before freight | 66.7% |
Worked example only. The £18 case cost and £1.50 shelf price are hypothetical figures, not live product prices, guarantees or recommendations.
Get the UK VAT calculation right before comparing prices
UK soft drinks, including ordinary carbonated energy drinks and colas, are generally standard-rated for VAT. HMRC’s food products VAT notice explains the rules and exceptions. For a VAT-registered retailer entitled to reclaim input VAT, use the ex-VAT buying cost and the ex-VAT selling price when calculating a normal gross margin. The VAT shown on the invoice and collected at the till is not the same thing as money earned from the product. If your business is not VAT-registered, input VAT may instead form part of your costs and you would calculate using the amounts actually paid and received; check your circumstances with your accountant, especially if you sell products with different VAT treatments.
One practical habit avoids a lot of confusion: write “ex VAT” or “inc VAT” alongside every price in your stock spreadsheet. A supplier’s £18 wholesale case and a customer’s £1.50 shelf price cannot be compared directly until both figures are on a consistent basis.
Delivery changes your landed cost—and your margin
The case cost is only the beginning. Pallet delivery, a tail-lift or handling charge, and any other directly attributable cost that you cannot recover should be included when you work out what your drinks actually cost to put on sale. Imagine a 90-case pallet of 24-can drinks with an illustrative £108 delivery charge excluding VAT. That works out at £1.20 freight per case, or 5p per can. Our £0.75 example buying cost therefore becomes £0.80 landed cost per can. At a net selling price of £1.25, gross profit falls to £0.45 per can and the margin falls from 40% to 36%. No wholesale price changed: the difference came entirely from including delivery.
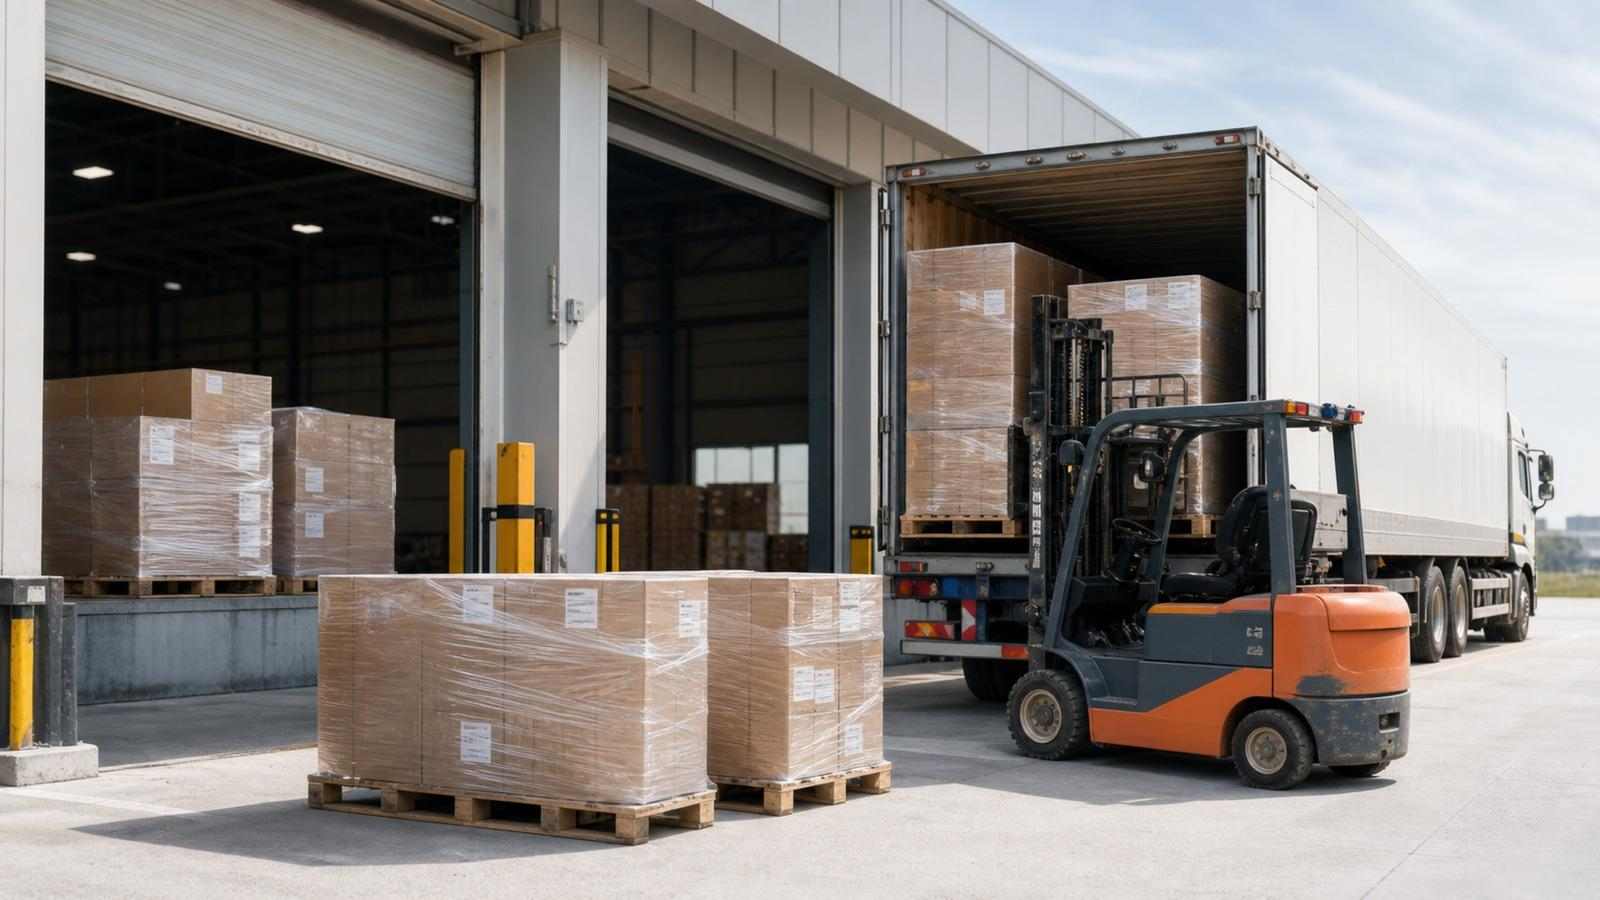
For a reliable figure, divide the whole landed cost of the order by the number of saleable cans, not simply the number of cases printed on a quotation. The retailer who checks freight, unloading arrangements and delivery access early is less likely to find a surprise cost after approving an order. TRIMAYU’s pallet-order information explains the practical side of ordering drinks by the pallet.
Work backwards from the margin you want to achieve
It can be easier to start with the shelf price your customers will accept and calculate the most you can afford to pay. Suppose your hypothetical shelf price remains £1.50 including VAT, so your net revenue is £1.25, and you are aiming for a 35% gross margin on that product. The maximum landed cost is £1.25 × (1 − 0.35) = £0.8125 per can, or £19.50 for 24 cans. If your delivery allowance is 5p per can (£1.20 per case), the maximum goods-only price would be £18.30 per 24-can case excluding VAT. This is a budgeting illustration, not a suggested industry-standard margin or a quotation.
That calculation helps you decide whether a case price works before tying up cash in stock. It is especially useful when comparing different case sizes. A 12-can case might look cheaper on the invoice while costing more per can—or the reverse. The relevant number is the delivered, saleable unit cost. Our Monster Energy 12-can versus 24-can guide shows why case format and pallet quantities matter when comparing wholesale offers.
The costs that quietly eat into drinks profitability
Gross margin is not the same as the money you take home. Staff wages, premises costs, card fees, refrigeration, waste, discounting and the time spent handling stock still have to be covered. If a few cans arrive damaged or pass their best-before date before being sold, the effective cost per saleable unit rises. For perspective, a £18 case with 24 cans costs 75p per can before freight; if only 22 cans are saleable, the purchase cost alone becomes about 81.8p per saleable can. That small change can undo part of a carefully planned margin. Monitor sell-through by flavour rather than assuming every variant will move at the same rate.
These are live concerns for independent retailers. The Association of Convenience Stores’ 2026 Local Shop Report highlights the pressure that operating costs and inflation have placed on local shops. It is a reminder to track both the gross margin on a drink and the overall profitability of the shop. One popular product may deliver a modest per-can margin but sell steadily; another may have a more appealing theoretical margin yet occupy space for weeks. You need both figures to make a sensible buying decision.
Make the numbers part of every wholesale order
Before placing your next order, ask for the exact product and case size, the number of cases, the ex-VAT price, the full delivered amount, remaining shelf life and any unloading requirements. Then enter four numbers into a spreadsheet: units, landed cost, expected net selling price and expected sell-through. The result is a much more useful buying decision than choosing whichever supplier advertises the lowest headline case price. Price-marked packs deserve special attention because the printed price can limit your practical shelf-pricing options in customers’ eyes.
If you are comparing energy drinks for your store, look at TRIMAYU’s wholesale energy-drinks range and use your own shelf prices to test the economics. When you know which flavours, formats and quantities fit your shop, request a wholesale quotation with your delivery postcode and unloading requirements. That gives you the actual landed cost you need to calculate a defensible margin—without guessing.
[…] Here the bottle delivers more gross profit per sale but a lower percentage margin. Which is preferable depends on the weekly units sold and the space each format uses. Remember that standard UK VAT applies to carbonated cola; for a VAT-registered business able to reclaim input VAT, the relevant comparison usually uses ex-VAT buying and selling values. HMRC’s VAT Notice 701/14 sets out the treatment of soft drinks. Add any attributable freight, handling and unsaleable stock to the buying-cost side before making a final margin decision. Your own VAT status and accounting arrangements may differ. For more on margin versus markup, see our wholesale drinks profit-margin guide. […]
[…] in the count of saleable stock. If you want to measure profitability as well as availability, our wholesale drinks margin guide shows how freight and the actual unit cost affect the return on an […]
[…] Every price in this table is hypothetical. The two case prices, delivery allowance and shelf prices are examples to demonstrate the calculation, not verified current offers, manufacturer recommended prices or TRIMAYU quotations. If the actual delivered costs were reversed, the profit result could reverse too. A higher margin on paper is not enough to decide the winner: the drink has to sell. For a deeper explanation of gross margin versus markup, see our UK wholesale drinks profit-margin guide. […]